
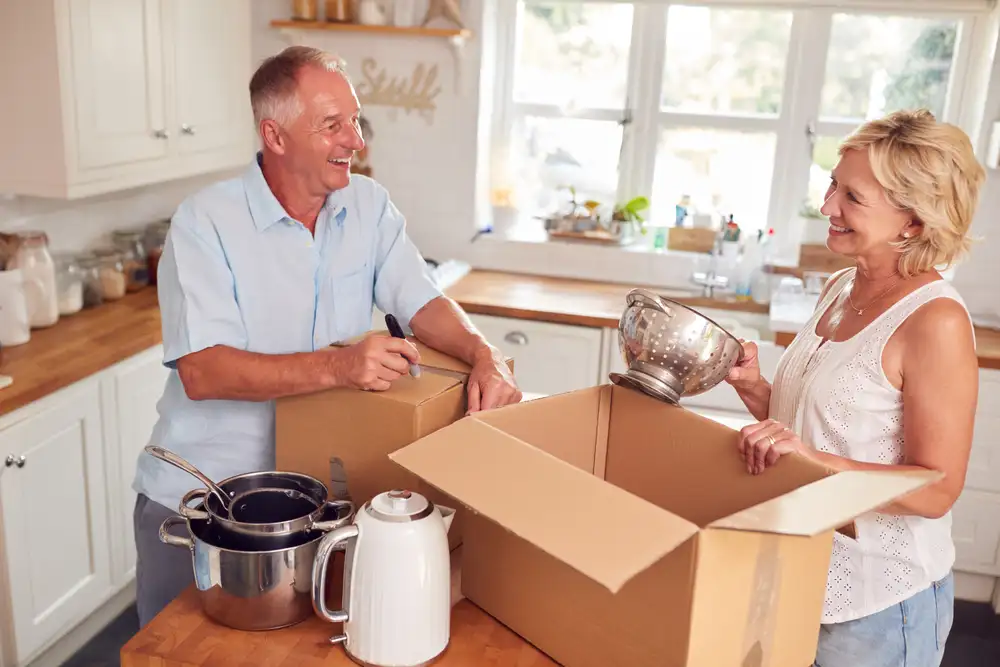
For busy mid-career homeowners and empty nesters juggling rising costs, crowded schedules, and homes that feel harder to maintain each year, downsizing can feel like a forced trade-off. The core tension is real: letting go of space and possessions can trigger stress, uncertainty, and second-guessing. Yet the most overlooked downsizing benefits go beyond square footage, creating financial flexibility, simplified living, and room for lifestyle changes that match what matters now. For general readers, the goal isn’t “less,” it’s fresh start opportunities.
What Downsizing Really Means in Practice
Downsizing is the downsizing process of moving into a home that fits your life now, not your past. In practice, it follows three principles: cut recurring costs, use space on purpose, and keep only what supports your current routines.
This matters because cost reduction can free monthly cash for goals you have postponed, from travel to debt payoff. Space optimization reduces cleaning, repairs, and decision fatigue, so your time feels more usable. Lifestyle simplification makes daily life easier to run, with fewer items to manage and fewer rooms to “maintain.”
Picture a couple who rarely uses their formal dining room and guest suite. They choose a smaller, more manageable abode, sell duplicates, and set up one flexible room for guests or hobbies. They gain lower bills, quicker weekends, and a home that works like a tool. That new breathing room can be directed into a startup budget and smart filing choices.
Use Downsizing Savings to Plan a Small Business Launch
When downsizing lowers your monthly overhead, the extra breathing room can become seed money for a fresh start, like launching a small business built around a passion or new career direction. Start by mapping a simple budget for your venture: how much you can set aside up front, what you can cover monthly, and how long you can sustain early expenses while you build revenue. Next, choose how you’ll set the business up. Forming an LLC can be appealing because it separates your personal and business finances, offers liability protection, and often makes the business look more credible to clients and partners.
Then decide whether to file the LLC yourself or use a formation service. DIY filing can cost less in direct fees, but it takes more time, requires managing the paperwork yourself, and leaves more room for missed steps or filing errors; it tends to make the most sense if your situation is straightforward and you’re comfortable tracking requirements. A guided service can save time, reduce mistakes, and provide ongoing compliance support, which can be worth it if you’re busy, nervous about details, or want help staying on track, if you want a side-by-side comparison for Texas, check it out.
Practical Moves to Save More and Live Simpler
Downsizing works best when you treat it like a mini operating system for your life: fewer fixed costs, fewer decisions, and more cash available for what you actually want to build. Use these moves to turn a smaller footprint into lasting financial flexibility and simpler daily routines.
- Set a “new overhead” target before you move: Pick a maximum monthly housing-and-utilities number and treat it like a hard cap. A simple rule is to keep essentials (housing, utilities, insurance, basic transportation) under 60% of take-home pay so there’s room for saving, debt payoff, or a small-business runway. This keeps your downsizing from turning into “same spending, different address.”
- Run a one-page “freedom budget” for your savings goals: List your top 3 priorities (e.g., emergency fund, debt payoff, business startup costs), then assign each a monthly line item. Automate transfers the day after payday so you don’t “accidentally” spend the margin you created by downsizing. If you’re planning a small business launch, add a separate “business cash buffer” line so personal money doesn’t get mixed with early expenses.
- Cut recurring costs like a state budget review: Do a 30-minute subscription and bill audit and cancel or downgrade anything that doesn’t support your priorities. A useful mindset is the same logic behind leaders who vetoed nearly $1 billion in spending, if it’s not essential, it doesn’t get funded. Start with phone plans, streaming, memberships, and insurance riders you no longer need.
- Downsize your stuff using the “one-touch, one-home” rule: Touch each item once and decide: keep, sell, donate, recycle. For “keep,” assign it an actual storage location in your new space; if it can’t be given a home, it doesn’t come with you. This is the fastest way to reduce moving costs and prevent the clutter rebound that makes simplified home life feel temporary.
- Maximize living space with zones, not more furniture: Define 3–5 zones (sleep, work, meals, storage, hobbies) and make every item serve a zone. Use vertical storage first (shelves, hooks, stackable bins), then “dual-use” pieces (ottoman storage, folding table) only if they replace something else. The goal is fewer surfaces to manage, which lowers cleaning time and decision fatigue.
- Create a “two-week box” to lock in new lifestyle habits: Pack a small box with only what you need for the first 14 days: one set of dishes, a limited wardrobe, core toiletries, basic tools. Live from it while everything else stays sealed; if you never open a box in two weeks, it’s a strong candidate to sell or donate. This turns simplification into a habit instead of a one-time purge.
- Rebuild your spending rules around your smaller life: Set three guardrails: a 24-hour wait for non-essentials, a weekly cash-like allowance for fun spending, and a “one-in, one-out” policy for household items. Track results for 30 days and adjust, downsizing financial tips only stick when they become default behaviors. These habits also make it easier to decide how much you can safely invest in a side hustle without stressing your core budget.
Downsizing Questions People Ask Before Taking the Leap
Q: How do I know if it’s the right time to downsize?
A: It’s usually the right time when housing costs, maintenance, or commuting steals energy from your real priorities. Start by writing a clear “why” and a deadline for deciding. Then run the numbers on what you could save monthly and what that savings would fund.
Q: What should I do with all the extra stuff without feeling wasteful?
A: Sort items into sell, donate, recycle, and keep, and set a one-week deadline for each category. Sell higher-value items first to offset moving costs, then donate the rest quickly to avoid re-cluttering. Taking photos of sentimental objects can preserve the memory without keeping the bulk.
Q: How can I downsize without regretting what I let go?
A: Use a “maybe box” with a 30-day timer for anything you are unsure about. If you don’t retrieve it within the deadline, you have evidence you can live without it. This creates emotional safety while still making progress.
Q: Can downsizing really reduce stress, or will it just feel cramped?
A: It reduces stress when you match your space to your routines, not your old habits. Map your daily needs (sleep, work, meals, storage) and keep only what supports them. If a room feels tight, reduce furniture before adding organizers.
Q: Should I downsize first or pay off debt first?
A: If your housing costs are high, downsizing can speed up debt payoff by freeing cash every month. Build a small emergency cushion first so the move does not create new debt. Then direct the freed-up money to your highest-interest balances.
Build Momentum with a Simple 7-Day Downsizing Reset
Downsizing can feel daunting because every room holds decisions, emotions, and the fear of making the “wrong” call. The practical mindset is to focus on what supports the life ahead, using intentional choices to reduce clutter, simplify commitments, and prioritize what earns its space. The payoff is real: a clearer home, lower stress, easier routines, and empowerment through downsizing that makes a fresh start feel achievable. Downsizing works when every item and obligation must justify the life you want next.
Leave A Comment